

$80,000
The Percentage Deductible
A 2% wind & hail deductible on a $4M building means $80,000 out of pocket before the policy pays, per building, per storm.
An independent Houston agency for Texas commercial property. We compare established carriers and walk you through every term before you sign.
Licensed Texas insurance agency · No obligation · We reply within one business day
What Do You Own?
Shopping Centers
Strip centers, neighborhood plazas and single-tenant retail.
Gas Stations & C-Stores
Fueling stations, travel centers and convenience stores, with or without fuel.
Hotels & Motels
Branded and independent hotels, motels and extended-stay properties.
Apartments & Multifamily
Garden-style, mid-rise, student housing and small multifamily portfolios.
Warehouses & Industrial
Distribution, flex, light manufacturing and multi-tenant industrial.
Office & Medical
Class A–C office, medical office buildings and professional plazas.
Builders Risk
Ground-up builds, renovations and conversions for property owners.
Properties We Insure
See what tends to go wrong, and the coverage owners usually carry.
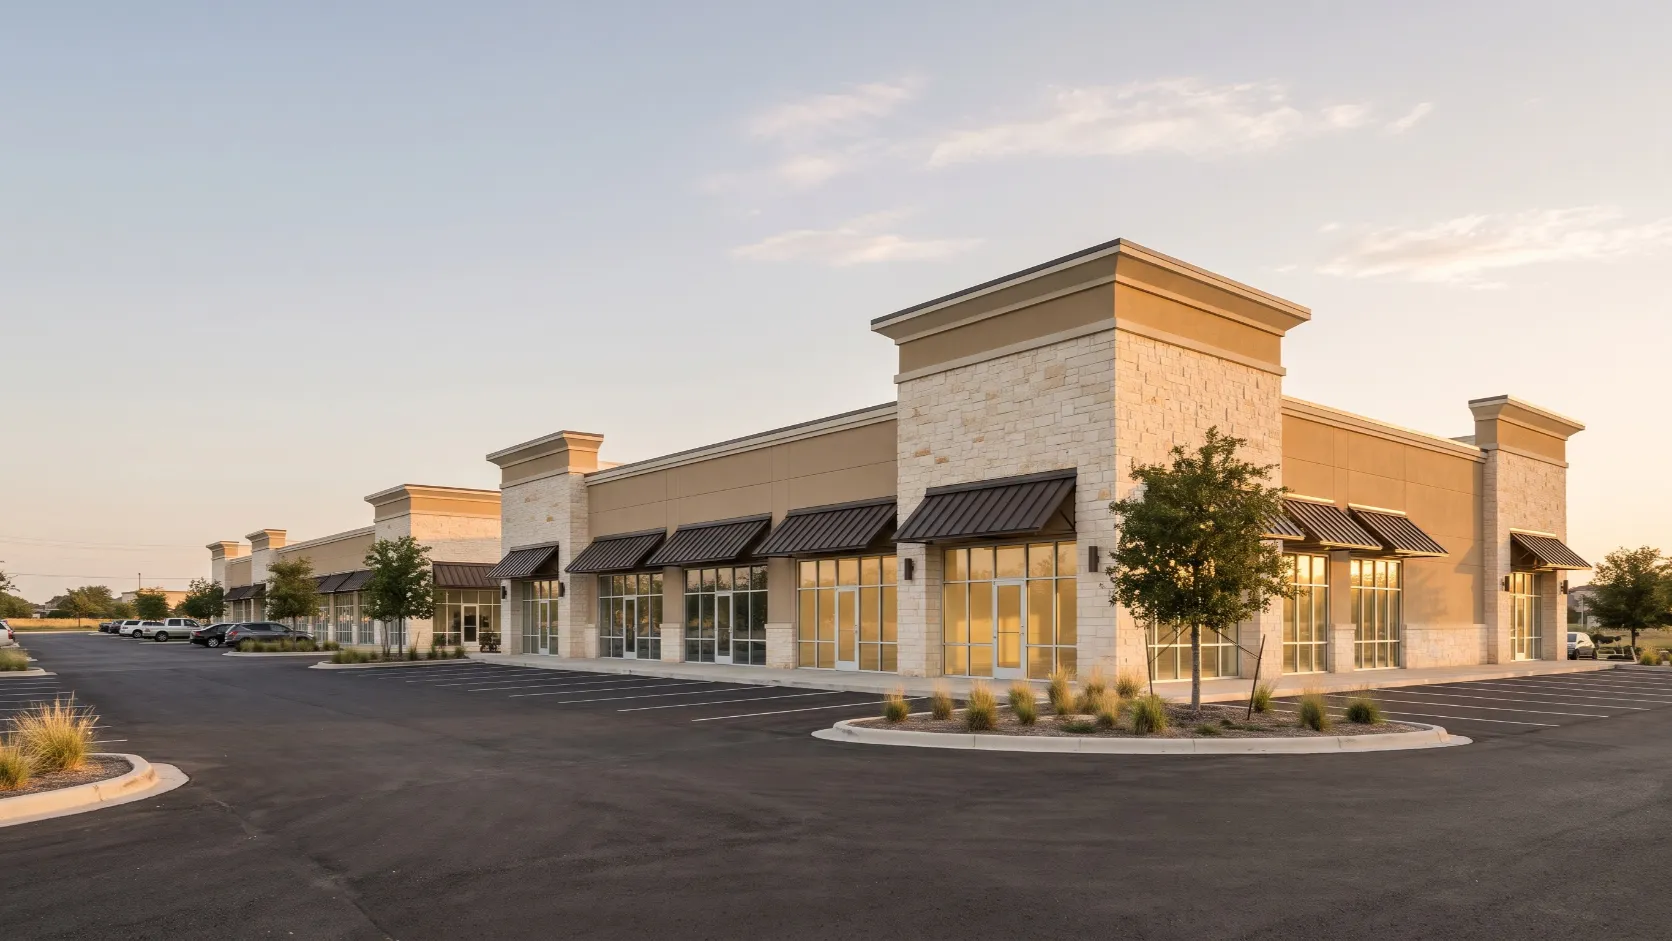 Shopping CentersStrip centers, neighborhood plazas and single-tenant retail.
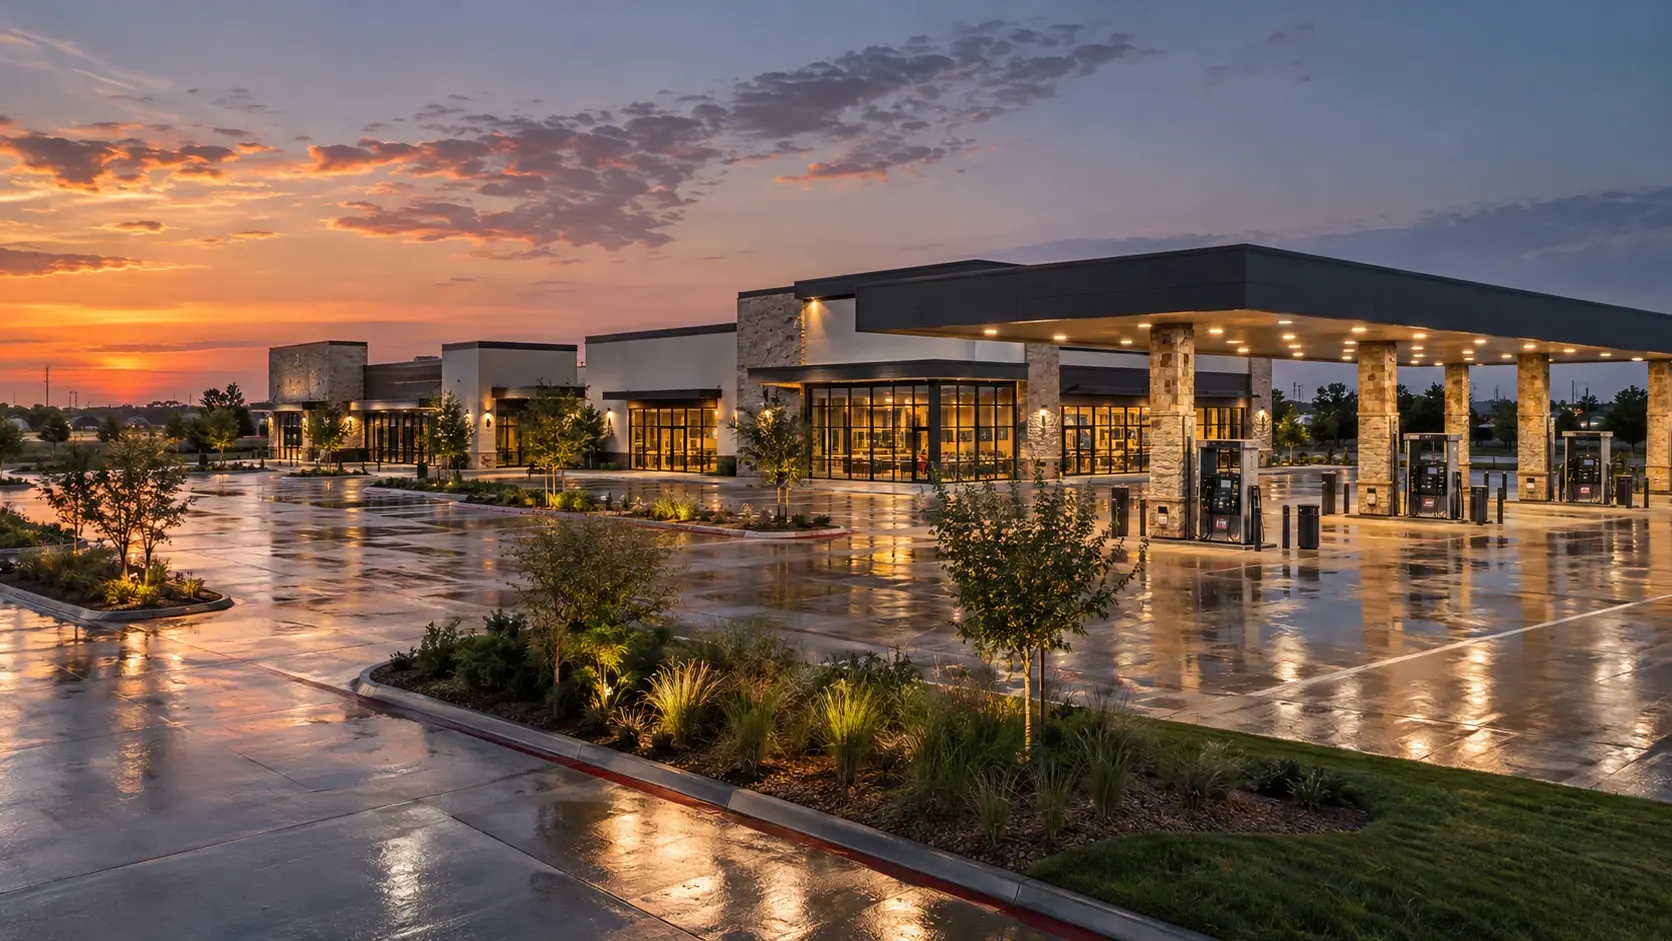 Gas Stations & C-StoresFueling stations, travel centers and convenience stores, with or without fuel.
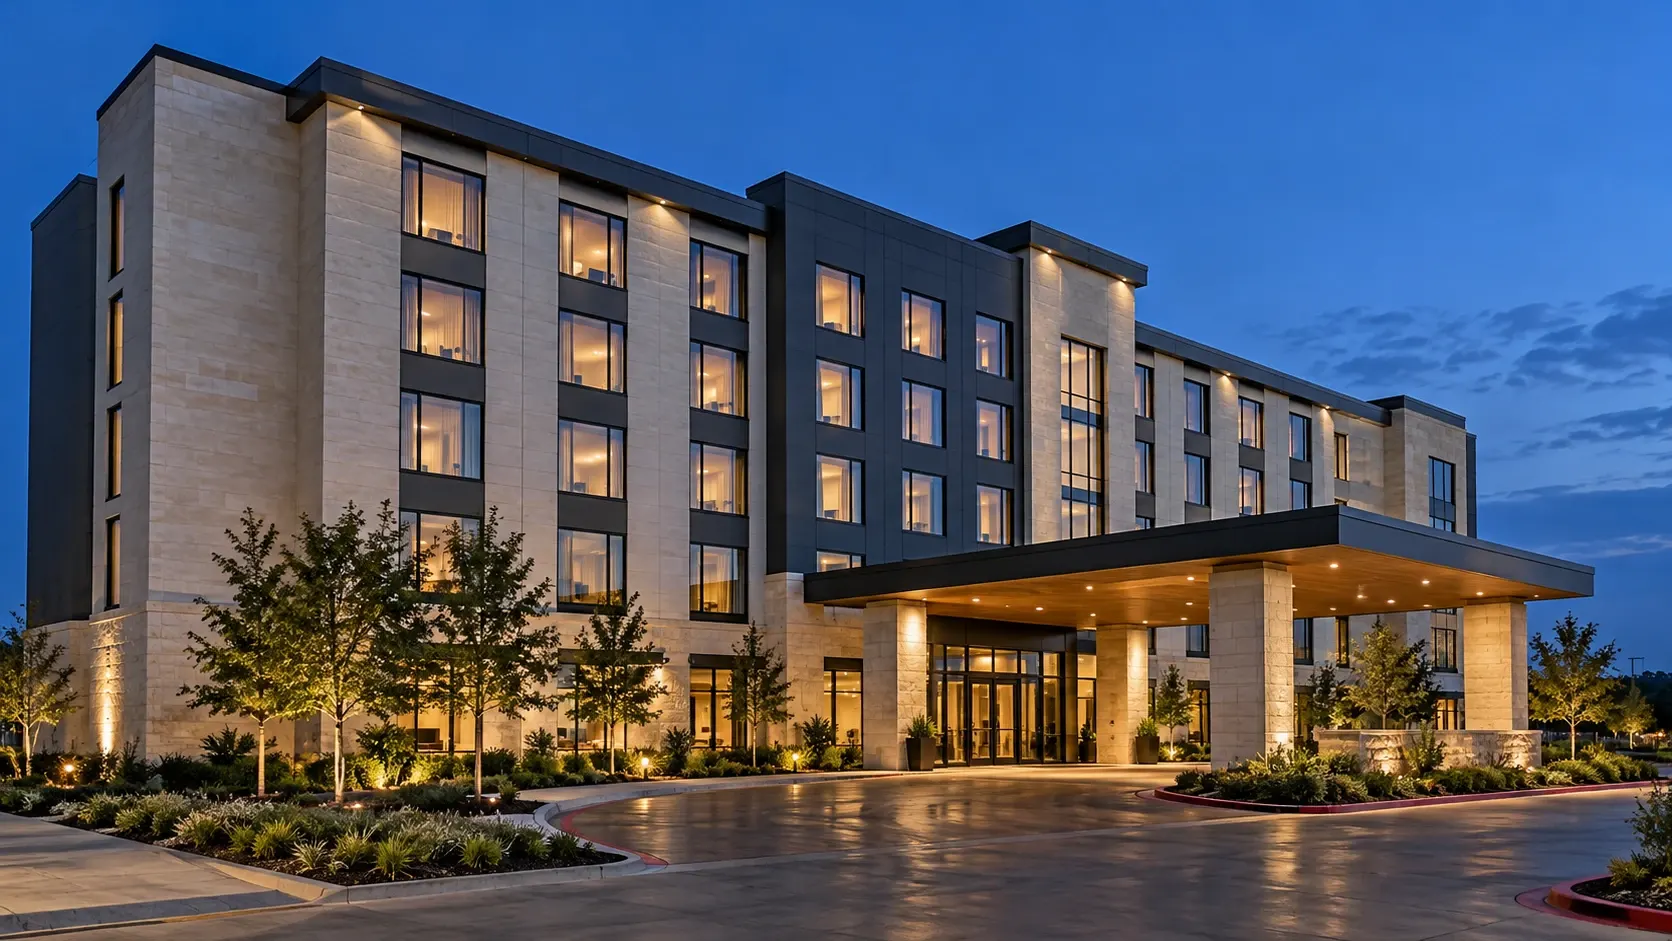 Hotels & MotelsBranded and independent hotels, motels and extended-stay properties.
 Apartments & MultifamilyGarden-style, mid-rise, student housing and small multifamily portfolios.
 Warehouses & IndustrialDistribution, flex, light manufacturing and multi-tenant industrial.
 Office & MedicalClass A–C office, medical office buildings and professional plazas.
 Builders RiskGround-up builds, renovations and conversions for property owners.
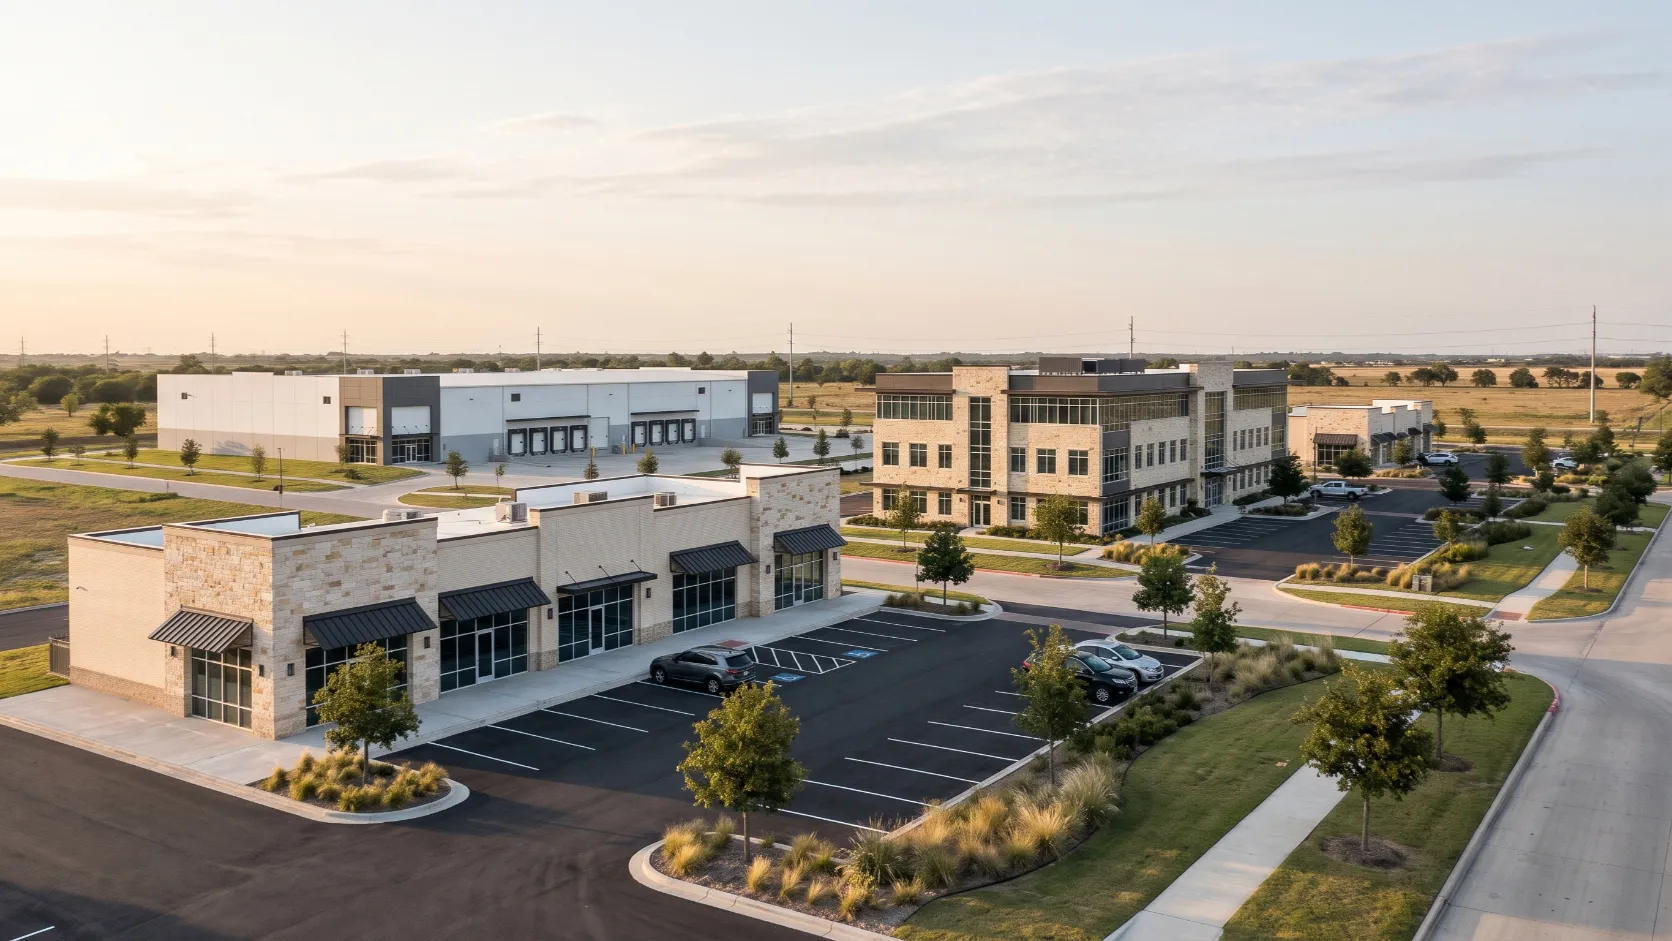 Multi-Property PortfoliosOwners and investors with several properties across Texas.
Our Standard
Standard and specialty carriers we place with directly or through wholesale partners.



The Fine Print
Worth reading before a storm, not after.
$80,000
A 2% wind & hail deductible on a $4M building means $80,000 out of pocket before the policy pays, per building, per storm.
−17%
Insure a $3M building for $2M under an 80% coinsurance clause and a $500,000 claim pays only about $417,000, before the deductible.
$500K
Property policies exclude flood, and NFIP commercial flood stops at $500,000 per building. Larger properties need excess or private flood.
Learn Before You Buy
Sourced guides and 277 plain-English insurance terms, each dated.
We specialize in Texas commercial property: shopping centers and retail plazas, gas stations and convenience stores, hotels and motels, apartments and multifamily, warehouses and industrial buildings, office and medical buildings, construction projects, and multi-property portfolios.
Yes. We're not tied to one insurance company. We compare established standard carriers and specialty (surplus lines) markets, then recommend the option that fits your property, your budget and your lender.
Our quote request takes about two minutes. We'll contact you within one business day to confirm details. Most commercial property quotes then take several business days, depending on the property and the carriers involved.
Just the basics to start: the property type, address and your contact details. For accurate quotes, we'll later ask for your current declarations pages, five years of loss runs (your claims history from your insurer) and, for multi-tenant properties, a rent roll.
Yes. Non-renewals happen, especially with older roofs, coastal properties and apartments. Call early: more time means more markets can quote.
Yes. We issue certificates of insurance and evidence of property for lenders, tenants and contractors, and we check your policy against your lender's written requirements.
Call us first. We'll help you document the loss, report it correctly, understand your deductibles and coverage, and stay in touch with the adjuster through the claim.