

Warehouse and industrial insurance for Texas owners.
Big roofs, changing tenants and vacancy, planned for before they matter. We value the building at rebuild cost and flag tenant changes carriers need to know.
Prefer to talk? Call (713) 367-1706
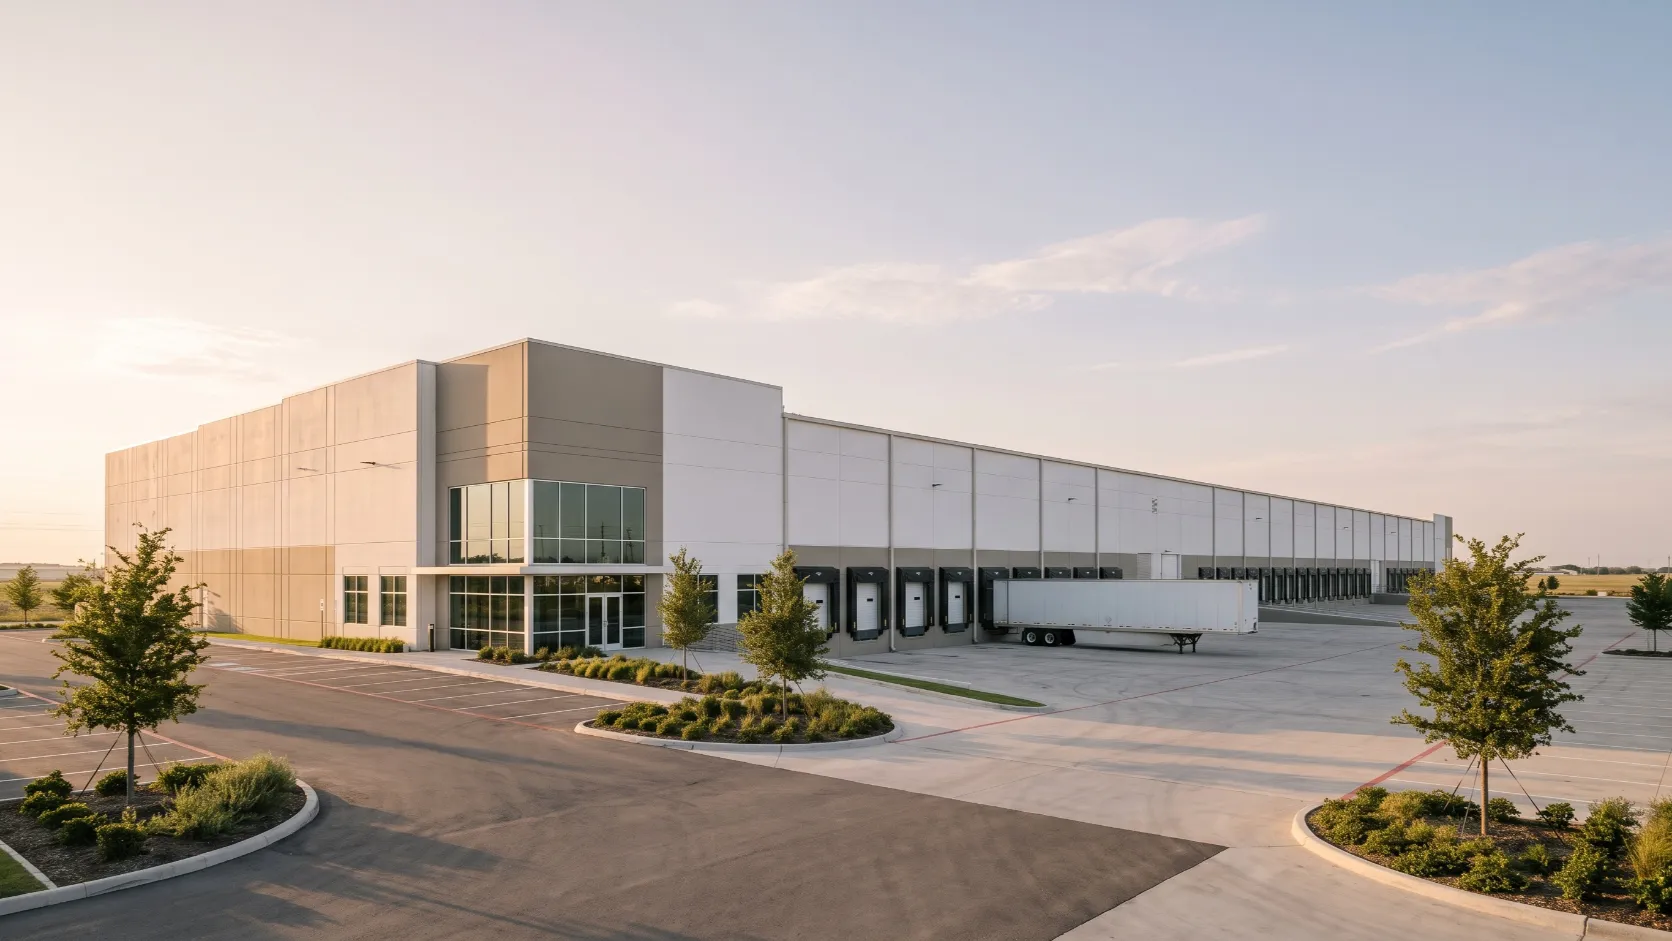
In Short
What insurance does a Texas warehouse or industrial building need?
Texas warehouse and industrial owners typically need building coverage at replacement cost, loss of rents, general liability, ordinance or law, equipment breakdown and often flood — plus a plan for vacancy between tenants, because standard property policies restrict coverage after 60 consecutive days vacant.
Read the complete warehouse or industrial building insurance guide
General information, not a promise of coverage.
Risks & Coverage
What can go wrong at a Texas warehouse or industrial building, and the coverage to consider.
- 01
Roof & Hail Exposure
Large metal and flat roofs take hail across the whole surface. Cosmetic-damage exclusions on metal roofs are common and need to be understood before you buy.
Coverage to ConsiderRoof terms — including cosmetic-damage exclusions — compared before you buy
- 02
Vacancy Clauses
Under a standard property form, a building left vacant for more than 60 days in a row loses coverage for vandalism, sprinkler leakage, glass breakage, water damage and theft, and other claims are reduced. Leasing gaps need planning.
Coverage to ConsiderA vacancy permit or vacant-building policy between tenants
- 03
Tenant Operations Change the Risk
A new tenant storing plastics or chemicals can change your sprinkler requirements and your rate. Carriers expect to be told.
Coverage to ConsiderTenant operations disclosed so the rate and sprinklers match
- 04
Sprinkler Leakage & Freeze
A frozen sprinkler line can flood an entire floor of stored goods. Heat, inspections and alarm monitoring all matter to underwriters.
Coverage to ConsiderSprinkler leakage, heat and alarm conditions understood
- 05
Code Upgrades After a Loss
Older industrial buildings often need code upgrades when they're rebuilt. Ordinance or law coverage can pay for it.
Coverage to ConsiderOrdinance or law coverage
Typical Coverage
What a Texas warehouse or industrial building usually carries.
- 01
Building — Replacement Cost
Shell, roof, docks and improvements at current construction cost.
- 02
Loss of Rents
Tenant rent replaced while the building is repaired.
- 03
General Liability
Third-party injury and damage claims at the property.
- 04
Ordinance or Law
Code-required upgrades and demolition after a loss.
- 05
Equipment Breakdown
Electrical service, switchgear, HVAC and dock equipment.
- 06
Vacancy Permit or Vacant Building Cover
Keeps coverage in place between tenants.
- 07
Umbrella / Excess Liability
Higher liability limits for multi-tenant and high-value sites.
- 08
Flood
Many industrial parks sit in or near floodplains.
Not Needed to Start
What to have ready.
Carriers price what they can see, so a complete submission helps them quote with confidence. Missing something? Send what you have.
- Square footage, clear height, construction and year built
- Tenants and what they store or make
- Sprinkler type (wet / dry / ESFR) and alarm monitoring
- Roof material, age and condition
- Current occupancy and any planned vacancies
- Five years of loss runs
- Lender's insurance requirements
Questions
Warehouses & Industrial: common questions.
What happens if my building sits empty between tenants?
Most property policies restrict coverage after 60 consecutive days of vacancy. We can add a vacancy permit or move the building to a vacant-property policy so you stay covered while you lease it up.
Do I need to tell my insurer about a new tenant?
Yes. What a tenant does or stores can change the fire risk, the sprinkler requirements and the rate. Telling the carrier up front avoids a claim dispute later.
How do carriers handle metal roofs and hail?
Many add a cosmetic-damage exclusion, so dents that don't let water in aren't paid. We show you which quotes include that exclusion and what it means for your building.
Ready When You Are
Your quote starts here.
About two minutes. A person reads every request.
Guides for Warehouses & Industrial